Share
21 of 29 EU countries froze minimum wages while inflation rose
2026. 08. 06.
4 min
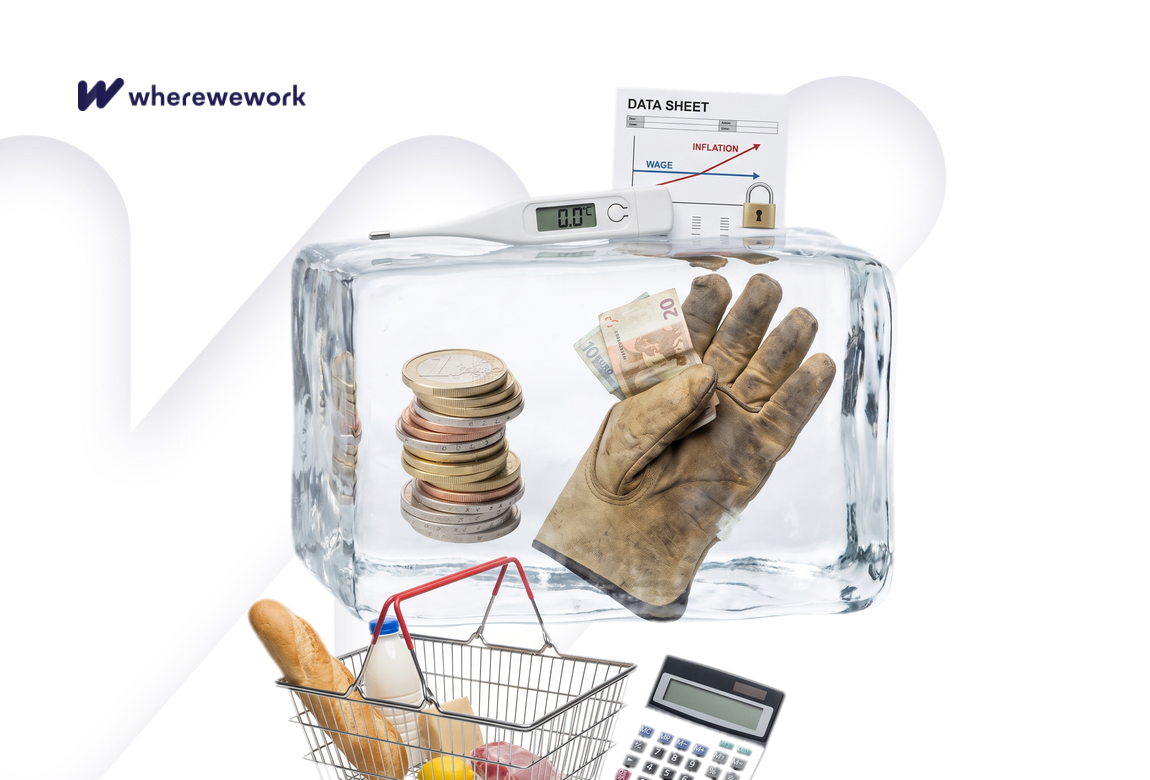
Eurostat's second-half 2026 release lands with a signal HR teams cannot afford to misread: of 29 European countries surveyed, only 8 raised their gross statutory minimum wage between January and July 2026. The other 21 held their floors flat while eurozone consumer inflation ran at 3.2% over the same half-year. For roughly 40 million minimum-wage earners across the EU and candidate countries, real purchasing power is quietly contracting, and the pressure is showing up at the bottom of every compensation band HR owns.
This matters for Hungarian HR leaders on two fronts. First, Hungary sits fourth from the bottom of the EU nominal ranking at €906, ahead only of Romania, Latvia and Bulgaria, according to Eurostat data referenced in domestic coverage. Second, the gap between statutory floor and market rate is wider than most benchmark decks acknowledge, and candidates now read that gap in real time.
The 2026 European minimum wage map, in nominal terms
In July 2026, Luxembourg led Europe with a gross monthly minimum wage of €2,771, per Eurostat figures. The high-band cluster continues with Ireland at €2,391, Germany at €2,343, the Netherlands at €2,338 and Belgium at €2,234. France sat mid-high at €1,867.
The mid-tier tells a more interesting story for regional recruiters: Slovenia €1,482, Spain €1,425, Lithuania €1,153, Poland €1,119, Cyprus €1,088, Greece €1,073, Portugal €1,073, Croatia €1,050. Close to the symbolic €1,000 line sit Malta €994, Estonia €946, Czechia €923, Slovakia €915 and Hungary €906. Bulgaria anchors the EU floor at €620. Among candidate countries, Turkey stands at €621, North Macedonia €624, Montenegro €670 and Serbia €743. Ukraine and Moldova mark the bottom of the wider European field at €169 and €313 respectively.
Five EU members, Italy, Denmark, Sweden, Austria and Finland, still operate without a statutory minimum wage, relying on sectoral collective bargaining instead. HR teams recruiting across those markets need to benchmark against collective agreement floors, not statutory ones.
Purchasing power tells a different story
Nominal euro figures flatter high-cost economies and punish low-cost ones. Adjusted for purchasing power standard (PPS), the ranking reshuffles meaningfully. The top five: Germany 2,164 PPS, Luxembourg 2,108, Netherlands 2,023, Belgium 1,922 and Ireland 1,756. Estonia becomes the lowest EU country at 935 PPS, closely followed by Latvia at 938. The range runs from 705 in Albania to 2,164 in Germany.
Two candidate countries, North Macedonia at 1,142 PPS and Serbia at 1,094 PPS, now rank above seven EU members including Malta, Slovakia, Hungary and Czechia. Romania climbed from 20th to 12th in the nominal-to-PPS reshuffle, and North Macedonia from 24th to 16th, each improving eight positions. Estonia was the biggest loser, sliding from 16th nominal to 26th on PPS. Latvia, Czechia and Cyprus each dropped four positions. Hungary, per domestic reporting, sits sixth from the bottom on PPS, overtaking Czechia and Estonia.
For HR teams running pan-regional comp bands, the practical read is this: nominal benchmarks understate the real cost-competitiveness of Central and Eastern European hubs, and overstate it for the Baltic economies. If your workforce planning still leans on gross-euro tables, you are pricing talent against the wrong denominator.
Where the floor moved, and where it didn't
The eight countries that raised statutory minimum wages between January and July 2026, in local currency, were North Macedonia (6.9%), Romania (6.8%), Estonia (6.8%), Belgium (5.8%), Greece (4.5%), Luxembourg (2.5%), France (2.4%) and the Netherlands (1.9%). Read against 3.2% eurozone inflation, only four of those increases outpaced the price level, and several by narrow margins.
The picture darkens in markets where inflation ran well above the eurozone average. Malta posted 8.2% inflation over the January to July window, Cyprus 5.4%, the Netherlands 4.7%. Malta and Cyprus did not raise their statutory floors during that period. Turkey is the outlier: 17.8% inflation between December 2025 and June 2026, and nearly 40% of the workforce earning minimum wage, the highest share in Europe. Any employer branding narrative that leans on “competitive base pay” in those markets needs stress-testing against actual local price levels, not headline euro figures.
What this means for HR in Hungary
Hungary's position is more nuanced than the nominal ranking suggests. From 1 January 2026, the gross minimum wage is 322,800 forints and the guaranteed wage minimum is 373,200 forints gross, per the domestic figures cited above. May gross average earnings reached 764,100 forints according to KSH. Real wages, per an OECD employment report referenced in the same coverage, rose 30% since 2021 and 14% over the past year, driven partly by forint appreciation that lifted the July minimum-wage figure to €906 in euro terms.
That combination, a modest nominal floor, meaningful real-wage growth, a favourable PPS position relative to Czechia and Estonia, creates a specific recruitment dynamic. Entry-level candidates are more sensitive to the gap between the statutory 322,800 forints and the market rate for their role than to the euro-equivalent number. HR teams that anchor offers to the statutory floor plus a small premium are competing against employers who benchmark to the KSH average and pay accordingly. The retention risk concentrates on new hires within the first 12 to 18 months, when the perceived offer-to-market gap is easiest to close by leaving.
Three implications for compensation and workforce planning
Rebase your regional benchmarks on PPS, not nominal euros. If your compensation committee reviews pan-European bands using gross-euro tables, you are systematically over-paying in high-cost Baltic markets and under-paying in Central Europe and the Western Balkans. The 8-position swing Romania and North Macedonia post between nominal and PPS rankings is not a rounding error, it is a structural reality your workforce planning should reflect.
Recalibrate the floor-to-median gap in each market. Where statutory minimums froze against 3.2% inflation, the real gap between your entry offer and the local median widened without any deliberate policy change on your side. In markets like Malta or Cyprus, where inflation ran materially above the eurozone average and floors did not move, that gap widened faster. Candidates read this. Retention data will follow.
Model FX exposure in your comp bands. Hungary's climb in the nominal ranking came partly from forint appreciation, not policy. Multi-currency employers who lock offers in euro and pay in local currency (or vice versa) carry a comp-band risk that is invisible on the org chart but real on the payroll line. Quarterly FX reviews of the entry-band range are cheap insurance.
The signal underneath the numbers
Twenty-one European countries chose not to move their statutory floor in the first half of 2026 while prices kept moving. That is a policy signal HR teams should not confuse with a market signal. Statutory floors set the legal minimum, market rates set the retention curve, and the space between them is where employer branding either earns trust or loses it. The compensation decisions HR takes in the next two quarters will be judged against the real purchasing power of the offer, not the number on the contract.
Share
What I read is worth it:
Read all the articles about
International Labour market Negotiation Workforce planning Statistics Editorial HR MetricsArticle written by:
 wherewework.hu
Comments
0 comments
No comments! Be the first to comment on this article!
Access your account and add your comment
International
Subscribe to the Newsletter
Read articles of interest from wherewework.hu contributors
