Share
Hungarian employers can top up 100,000 HUF school-start aid
2026. 08. 12.
4 min
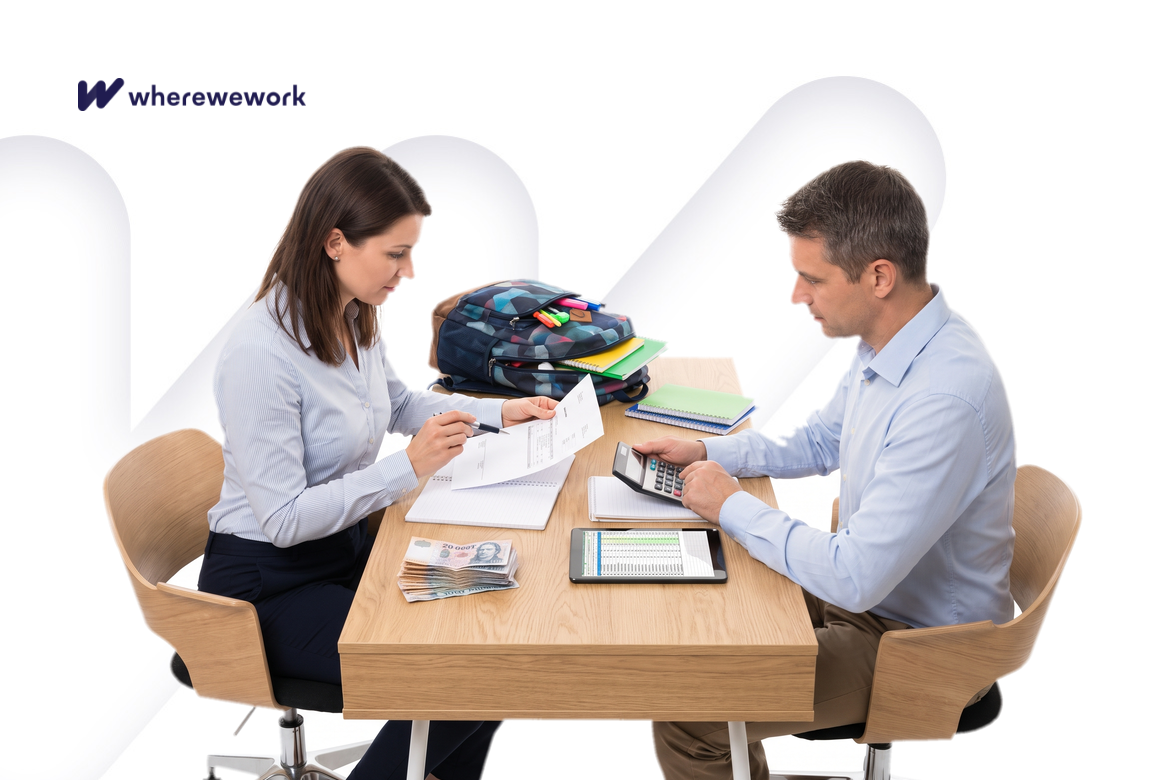
Roughly 400,000 Hungarian pupils will receive HUF 100,000 in state back-to-school support this autumn, half of it paid out by 24 August 2026 through the Magyar Államkincstár (Hungarian State Treasury) and the remaining half arriving as a back-to-school voucher by 30 November 2026. That grant is now formally tax-exempt after a 24 July 2026 amendment to the personal income tax act. What isn’t tax-exempt is the money your employer might hand you on top of it.
If your company is planning a September gesture, whether that’s cash, a voucher, or a school bag, the payroll consequences are not intuitive. Employees see a smaller net figure than expected. HR budgets swell beyond the sticker price. Both sides need the same maths in front of them before September payslips land.
What the state grant covers, and what it doesn’t
The autumn 2026 back-to-school support is a government-decree payment worth HUF 100,000 per pupil, targeted at roughly 400,000 children and their working parents. The Treasury releases 50% by 24 August 2026, with the remaining half delivered as a back-to-school voucher no later than 30 November 2026.
On 24 July 2026, Annex 1, Point 1, Sub-point 5 of the Hungarian personal income tax (szja) act was amended to declare this specific government-decree support tax-exempt. That exemption is narrow: it applies to the state grant itself. It does not extend to any additional amount an employer decides to layer on top.
This is the point most parents and quite a few HR teams miss when they hear “tax-free back-to-school support” in a headline. The tax-free label attaches to the government’s payment. Anything your workplace adds runs through a completely different set of rules.
For employees: what an employer top-up actually nets you
If your employer offers a cash contribution towards your child’s school costs, that money counts as employment income and is taxed as non-regular income. In practical terms, before the transfer reaches your account, the payroll team must withhold 15% personal income tax advance and 18.5% employee social contributions.
Take a HUF 50,000 cash top-up as a worked example. The 15% PIT advance is HUF 7,500. The 18.5% social contributions are HUF 9,250. Your net arrives at HUF 33,250, not HUF 50,000. On a HUF 100,000 employer gesture, the same maths lands you at HUF 66,500 in hand.
In-kind gifts do not solve this. If your employer gives you a school bag, a voucher, or any tangible benefit tied to back-to-school costs, paragraphs 46(7) to 46(10) of the personal income tax act still trigger a PIT advance and contribution obligation, even when withholding from the object itself is physically impossible. The value still counts as income; the withholding just has to be settled through your next payslip.
Two practical steps before you sign off on any offer letter this autumn. First, ask HR for the gross-to-net breakdown of any back-to-school benefit in writing. Second, if you are negotiating a compensation package this quarter, treat these top-ups the way you would any bonus line, taxable, worth confirming, and worth comparing against a straight base-pay adjustment. The same logic applies to any wages component that carries similar withholding.
For HR and payroll: the true employer cost of a “nice gesture”
The headline figure and the true cost of a back-to-school top-up diverge in a way that catches even experienced payroll teams. On top of the 15% PIT advance and 18.5% employee social contributions withheld from the employee, the employer pays 13% social contribution tax (szocho) on the same base. Every HUF 100 of gross top-up therefore costs the company HUF 113 before administration.
Model this against a HUF 50,000 employer contribution per employee. The employee nets HUF 33,250. The employer’s outlay is HUF 56,500 (HUF 50,000 plus 13% szocho of HUF 6,500). At HUF 100,000 per employee, the outlay rises to HUF 113,000 for a net-to-employee of HUF 66,500. The gap between what leaves the company account and what lands in the employee’s account is roughly HUF 46,500 per person on the higher figure, or nearly half.
The in-kind alternative deserves a careful read of paragraphs 46(7) to 46(10). Giving a school bag or a retail voucher does not remove the withholding obligation; it simply shifts the mechanics. The PIT advance and contributions must still be settled, typically against the employee’s next cash wages. One narrow relief point: no interest-differential PIT or szocho liability arises for the payer if the receivable from the in-kind benefit is settled within six months.
For HR teams shaping a 2026 parent-support programme, three decisions warrant explicit sign-off before September payroll runs:
- Budget on the loaded cost, not the gross. A HUF 5 million pot for 100 employees at HUF 50,000 each is really HUF 5.65 million once szocho lands. Approve the number that leaves the account.
- Communicate the net figure to staff. Announcing “HUF 50,000 back-to-school support” invites disappointment when payslips show HUF 33,250. Either lead with the net or gross up the payment so the announced number is what arrives.
- Document the in-kind mechanics. If the plan is vouchers or physical items, payroll needs to know when the withholding settles and against which payslip line, well before the item is handed out.
There is a legitimate policy question buried in the maths. If the goal is to help parents cover roughly HUF 100,000 of real costs and the state has already provided that amount tax-free, an employer top-up of HUF 20,000 to HUF 30,000 net may deliver more perceived value than HUF 50,000 gross, at a smaller and better-communicated employer cost. Some Hungarian HR teams are quietly reframing 2026 programmes around this ratio.
Key takeaways for September 2026
- The HUF 100,000 state back-to-school grant is tax-exempt following the 24 July 2026 szja amendment. Employer top-ups on top of it are not.
- Cash top-ups trigger 15% PIT advance plus 18.5% employee social contributions on the withholding side, and 13% szocho on the employer side.
- In-kind gifts (bags, vouchers) do not escape the withholding rules under paragraphs 46(7) to 46(10); they just shift when and how the contributions settle, with a six-month safe harbour on interest-differential liability.
- Employees should ask for a gross-to-net breakdown in writing. HR teams should budget on the loaded cost, not the announced gross.
Share
What I read is worth it:
Read all the articles about
Students Job opportunities Legislative Career planning Editorial Ekonomia HR Metrics Workforce planning Labour marketArticle written by:
 wherewework.hu
Comments
0 comments
No comments! Be the first to comment on this article!
Access your account and add your comment
Students
Subscribe to the Newsletter
Read articles of interest from wherewework.hu contributors
